Lido Lend, a proposed lending protocol from Lido contributors, may let ETH lenders shrink debtors’ positions earlier than liquidation if its closing guidelines make wholesome loans eligible for collateral withdrawals. Its Fallback Exits design would cowl a lender’s withdrawal shortfall with borrower collateral whereas decreasing the affected debt.
Within the ETH/wstETH instance within the October 16 disclosure, lenders provide ETH and debtors pledge wstETH to borrow it. An exit into that collateral would go away the lender uncovered to a staking token earlier than acquiring ETH. Actual borrower eligibility and the token-versus-claim supply interface stay unsettled.
Lido contributors launched the lending venture on October 7 as a modified fork of Morpho Blue constructed round remoted markets. Within the October 16 publish, contributor Izzy mentioned technical specs and market parameters would comply with inside two weeks, with governance processes and public audits nonetheless forward of mainnet launch.
Fallback Exits would put debtors nearest the liquidation loan-to-value ratio, or LLTV, first. A lot more healthy positions can be much less prone to provide collateral. That language suggests a potential unwind beneath the liquidation threshold; closing eligibility guidelines will decide whether or not these positions qualify.
The disclosure leaves the eligibility cutoff, settlement valuation, debt-offset components, charges and limits unspecified. The selection between direct collateral tokens and an intermediate declare additionally stays open. These particulars are consequential: eligibility determines whose place can shrink, whereas pricing determines the worth exchanged.
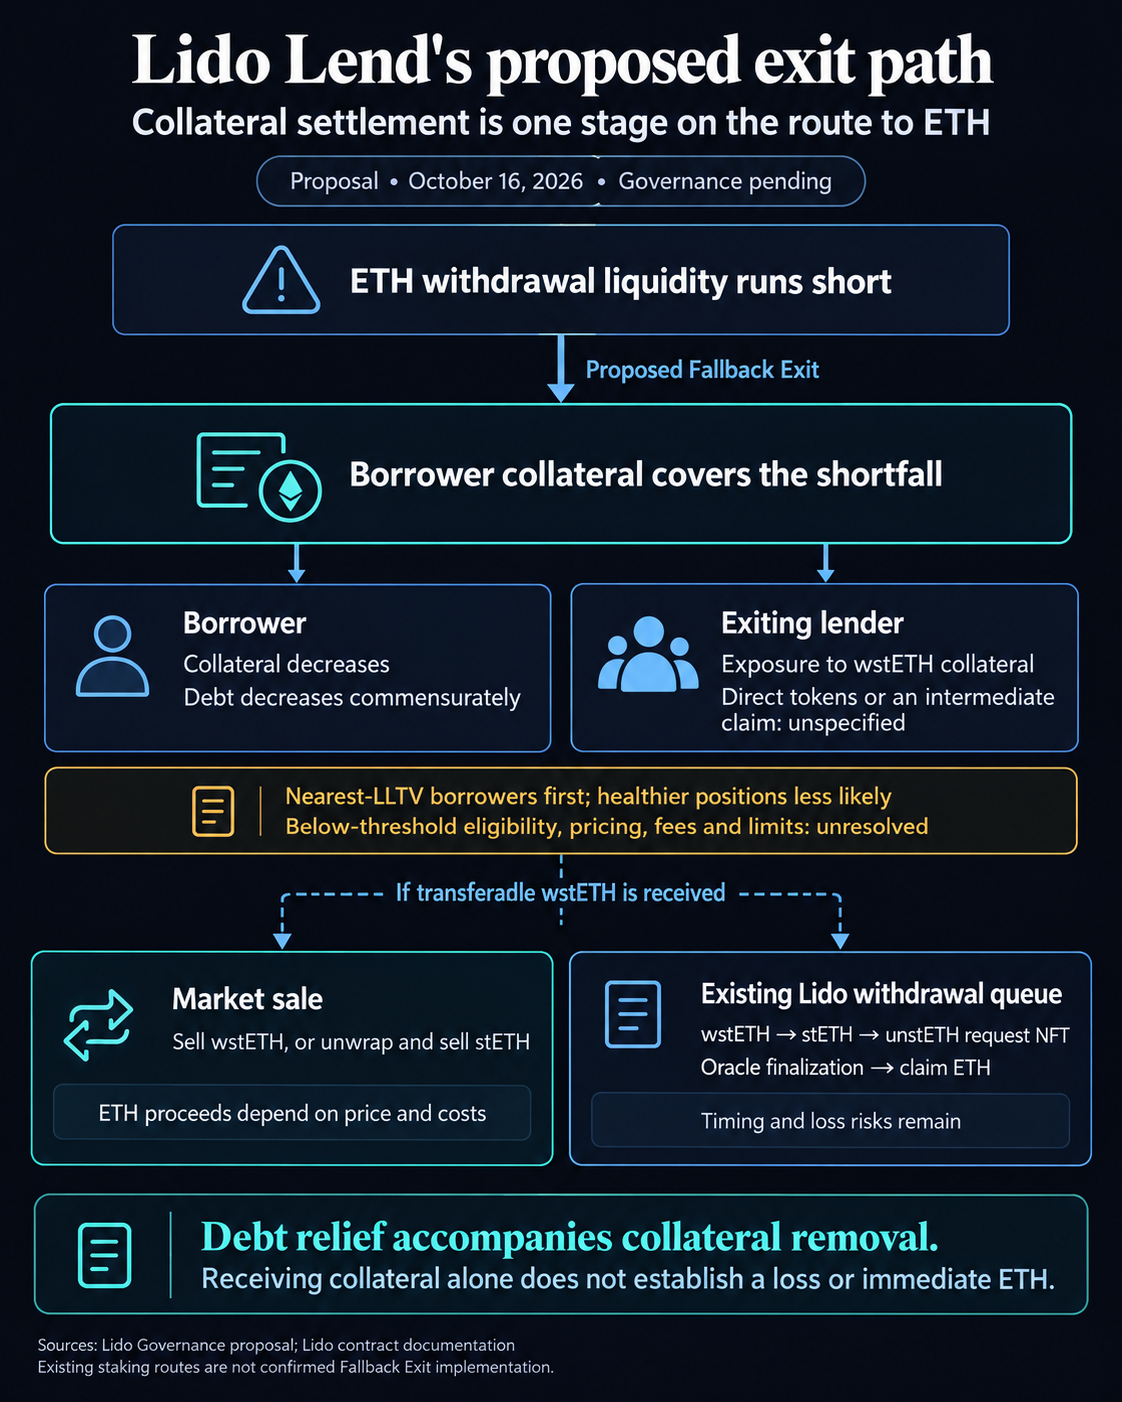
For a borrower, collateral leaving the place have to be thought of alongside the debt eliminated. A borrower’s fairness change and any penalty rely on the collateral valuation and corresponding debt aid.
The proposed recall threat considerations management over a place’s measurement in addition to its solvency. If below-threshold positions qualify, staying throughout the borrowing restrict may defend towards strange liquidation whereas leaving a borrower uncovered to a lender-driven discount.
Fallback Exits and Morpho’s withdrawal guidelines
Morpho Blue’s core contract illustrates the distinction. Its withdrawal perform accrues curiosity and reduces the lender’s provided stability. It then checks that the remaining provided belongings cowl whole borrowed belongings. If that protection is inadequate, the transaction reverts; a profitable withdrawal transfers the mortgage token.
It is a market-liquidity check. Borrower collateral stays exterior that withdrawal path, so a loan-token shortfall causes the withdrawal to revert. Compensation follows a separate path, bringing mortgage tokens into the contract whereas decreasing debt balances.
Liquidation applies one other check altogether. The contract compares debt with the collateral’s oracle worth multiplied by the market’s LLTV, together with its integer rounding. A place that continues to be inside that restrict is wholesome, together with equality within the contract’s examine, and the liquidation perform rejects it. A liquidator provides mortgage tokens in alternate for seized collateral.
The core code reserves liquidation for unhealthy positions, no matter a lender’s withdrawal wants. Lido’s proposed collateral settlement would introduce a distinct path to decreasing a place.
Morpho lenders even have a possible different to ready for repayments. Its Public Allocator V2 liquidity documentation describes shifting mortgage belongings from taking part vaults right into a goal market to help a bigger withdrawal.
That route depends upon the vaults’ settings, permissions, caps and obtainable belongings. A transfer could carry a penalty paid by the caller. Each liquidity already in a market and liquidity obtainable for reallocation are unreserved, so the displayed quantity can change earlier than execution.
Morpho recommends combining reallocation and withdrawal in an atomic transaction, refreshing the plan and simulating it earlier than submission. The comparability is subsequently between conditional routes: Morpho can deliver eligible mortgage liquidity right into a market; Lido proposes letting an exiting lender settle for publicity to borrower collateral.
From wstETH collateral to usable ETH
wstETH and ETH balances measure completely different belongings. Lido’s wrapper documentation describes a token whose stability stays mounted by oracle reviews whereas its stETH entitlement modifications. Unwrapping delivers stETH.
The wrapper’s conversion price measures a stETH entitlement. A market quote measures how a lot ETH a purchaser would pay.
If fallback settlement in the end provides a lender transferable wstETH, a sale would rely on the executable value and transaction prices. The accounting worth used to cancel debt and the precise ETH sale proceeds can differ. The identical distinction applies if the lender unwraps first after which sells stETH.
Lido’s current withdrawal queue gives one other route as soon as a holder has transferable collateral. It accepts wstETH, unwraps it into stETH and points an unstETH NFT representing the request. Finalization by an oracle report comes earlier than the holder can declare reserved ETH.
The present queue caps a stETH request at 1,000 stETH and checks wstETH requests by their stETH equal. Bigger quantities will be cut up into separate requests. These limits belong to current staking withdrawals; the proposed lending exit’s limits stay unspecified.
Finalization depends upon obtainable ETH, elapsed time and share-rate situations. Tokens cease incomes rewards whereas queued and stay uncovered to losses, which might scale back redemption worth. The lender’s route from a fallback settlement into that queue stays an implementation query.
CryptoSlate’s September 27 staking-token evaluation examined the excellence between promoting a token and redeeming for ETH. Its September 14 protection of lending withdrawals additionally defined how Morpho vault redemptions can depart a holder with underlying positions that stay illiquid.
Lido’s proposal provides the borrower’s aspect of that alternate: debt and collateral might be lowered to help another person’s withdrawal.
For an ETH lender, the helpful comparability is subsequently the asset obtained, the price of changing it and the time till ETH can be utilized. For a borrower, it’s the eligibility rule and the quantity of debt eliminated for the collateral taken.


