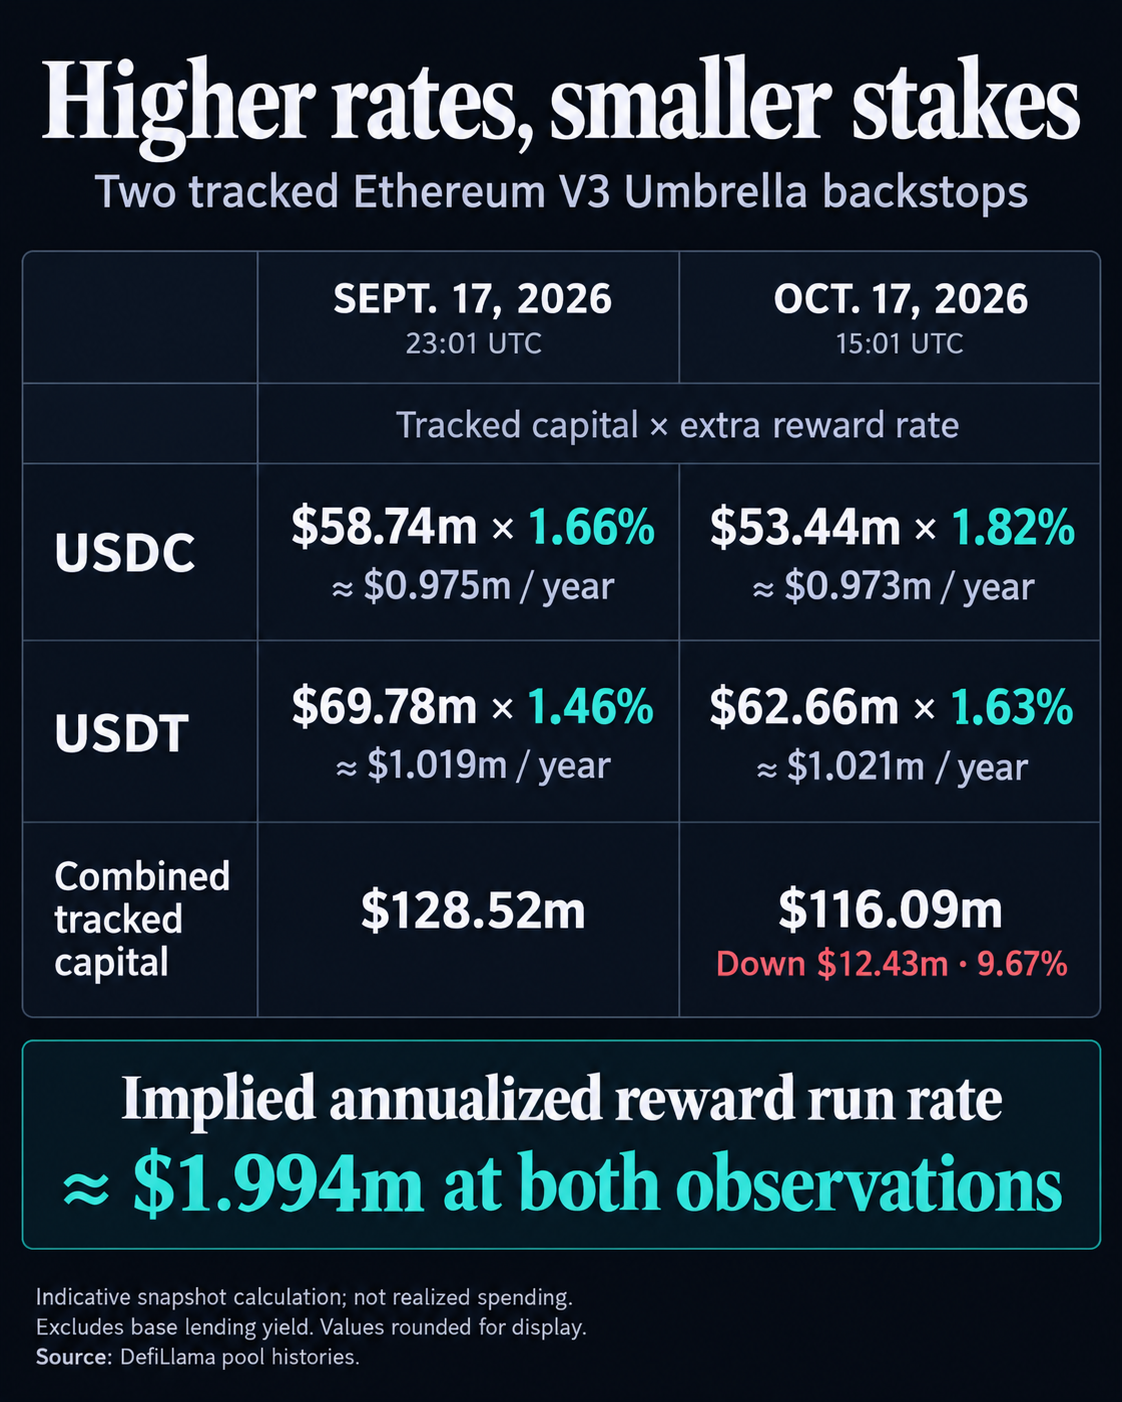
Aave’s two tracked Ethereum V3 stablecoin backstops shrank by $12.4 million between Sept. 17 and Oct. 17 at the same time as their further reward charges elevated. Collectively, the USDC and USDT positions held $116.09 million on the later commentary, down 9.67% from $128.52 million.
The positions belong to Umbrella, Aave’s system for utilizing staked property to soak up lending deficits. Members hold incomes underlying lending yield and obtain further rewards for accepting the chance that their stakes will probably be used to cowl losses.
The figures measure dollar-valued stakes. Their motion contains asset valuation in addition to adjustments within the quantity deposited, so a decline within the stability alone can’t establish withdrawals or losses.
Multiplying every place’s tracked greenback worth by its displayed further reward fee implies roughly $1.994 million annualized at each endpoints. A richer proportion fee coincided with much less tracked safety capital, whereas that indicative combination reward quantity barely moved.
DefiLlama’s USDC historical past information a decline from $58,739,617 to $53,437,993. Its USDT historical past reveals a fall from $69,783,937 to $62,655,694. These are reductions of $5.30 million and $7.13 million, respectively, including to $12,429,867.
Each comparisons use the Sept. 17 commentary at 23:01 UTC and the Oct. 17 commentary at 15:01 UTC, in 2026. The timestamps are barely lower than 30 days aside. The odds under are the extra reward element displayed for these observations.
Ethereum V3 Umbrella stakeCapital, Sept. 17Capital, Oct. 17Extra reward fee, Sept. 17Extra reward fee, Oct. 17USDC$58,739,617$53,437,9931.66percent1.82percentUSDT$69,783,937$62,655,6941.46percent1.63%
The tracked positions are wrapped-aToken Umbrella stakes on Ethereum V3. DefiLlama identifies them as stkwaEthUSDC.v1 and stkwaEthUSDT.v1; their token identities match the present Aave handle ebook.
The USDC further fee elevated by 0.16 proportion factors and the USDT fee by 0.17 factors. Lending yield moved individually: USDC’s base fee rose from about 3.60% to three.77%, whereas USDT’s elevated from about 3.02% to three.12%. The bottom element displays the lending return. The additional element compensates for staking and slashing danger; solely that element belongs on this safety-incentive calculation.
How the reward fee can rise
For every commentary, the calculation is the tracked greenback worth multiplied by the displayed further reward proportion, divided by 100, then summed throughout the 2 stakes.
Utilizing the September values offers $1,993,923.12 annualized. Utilizing the October values offers $1,993,859.28. Each spherical to $1.994 million.
These quantities are indicative annualized run charges derived from snapshots. Precise accrual and funds rely upon the trail of charges, stake values, reward configuration and participation over time.
Umbrella’s reward-controller documentation explains a mechanism by way of which the proportion fee can rise with out a bigger combination distribution. Its emission curve relates the quantity of rewards distributed to the quantity staked relative to a configured goal.
Mixture emissions attain their most on the goal. Between the goal and 120% of goal, emissions decline towards 80% of that most. At or above the 120% boundary, combination emissions are flat. In that area, fewer stakes can share the identical reward stream, growing the speed per unit of capital.
Beneath goal, the curve boosts rewards per unit to encourage participation, whereas combination emissions stay under their peak. The plateau supplies a technique for a smaller denominator to obtain a better proportion fee. Establishing whether or not it utilized to those swimming pools at each observations would require matched contract settings and balances; the histories alone go away that particular rationalization unresolved.
A Sept. 25 proposal from TokenLogic sought to resume the allowances used to pay Umbrella rewards whereas leaving emission charges, goal liquidity, cooldown parameters, deficit offsets and the Dec. 2, 2026 distribution finish unchanged.
The proposed allowances lined rewards already accrued however unclaimed, together with quantities owed to former stakers, plus remaining emissions by way of that distribution finish. They changed the remaining allowances. Studying these quantities as a contemporary annual incentive finances would subsequently mix previous obligations with potential funds.
What the smaller balances say about safety
Aave’s documentation confines staking danger to the related asset and community: USDC stake covers USDC deficits, whereas USDT stake serves its personal reserve. The mixed complete measures the dimensions of the 2 positions. Every reserve’s safety relies upon by itself allotted stake.
Slashing follows a realized reserve deficit that exceeds the relevant deficit offset. LlamaRisk’s protection rationalization describes that offset as a DAO-funded first-loss layer earlier than Umbrella stake is used.
The exit guidelines additionally matter to stakers weighing the additional return. Aave paperwork a 20-day cooldown adopted by a two-day withdrawal window. Rewards hold accruing throughout cooldown, and the stake stays uncovered to slashing whereas the holder waits.
The DefiLlama adapter values provider-reported complete property utilizing an related value. Wrapped aTokens have an alternate fee, so valuation is a part of the measured stability.
The excellence additionally applies to Aave’s separate V4 protection plans. CryptoSlate’s September reporting on the V4 proposal involved proposed targets for various safety modules. These targets concern totally different safety modules from the noticed V3 balances.
On the October commentary, the additional charges had been larger and the 2 tracked balances had been smaller. The inducement supply and the capital accompanying it had moved in reverse instructions.


