When a financial institution rejects your mortgage utility, you are likely to ask why, and if the reply says, “Your utility didn’t meet our inner danger standards,” that response might need been acceptable if a mortgage officer personally reviewed your utility. It turns into a lot tougher to defend when a man-made intelligence system analyses 1000’s of variables and produces the choice in milliseconds, however what precisely went incorrect?
Was your revenue too low? Was your compensation historical past weak? Did your transaction behaviour increase a danger flag? Did the mannequin use data you didn’t know was being thought-about? If the lender can’t reply these questions, the issue is greater than poor customer support. It turns into a query of due course of, equity, and accountability.
That is why AI finance regulation has turn out to be an vital side of finance. Monetary establishments don’t merely use AI to suggest services or products they provide. They use it to find out who receives credit score, how a lot they pay for insurance coverage, and the way monetary danger is assessed. The reason will not be merely a technical characteristic however more and more a authorized requirement and an ethical expectation.
The Authorized Foundations of a Proper to Rationalization
The thought of a proper to clarification for algorithmic credit score is commonly related to the European Union’s Normal Information Safety Regulation, significantly Article 22.
Article 22 restricts sure selections based mostly solely on automated processing the place these selections produce authorized or equally vital results. The GDPR additionally supplies people with data regarding the logic concerned in sure automated decision-making processes. Nevertheless, it will be important to not overstate this as a vast proper to obtain the supply code or each mathematical calculation behind an AI system.
The European Courtroom of Justice gave the problem significantly extra substance in its February 2025 judgment in Dun & Bradstreet Austria, which involved a person whose utility for a mobile-phone contract was rejected following an automatic evaluation of her creditworthiness. The Courtroom held that the individual was entitled to an evidence sufficiently detailed to grasp how the automated resolution had been reached and to problem it. The Courtroom additionally made clear that offering sophisticated mathematical data alone wouldn’t essentially fulfill the requirement, a distinction that issues as a result of the regulation doesn’t require a shopper to turn out to be a machine-learning engineer.
The individual ought to be capable to perceive what occurred to them and have a significant alternative to contest it, which is a essentially completely different thought from merely making an algorithm’s code out there.
Why Rationalization Is About Due Course of
The philosophical significance of clarification turns into clearer if we take into consideration due course of. In strange authorized proceedings, an individual affected by a choice is mostly given some account of why the choice was made. A decide doesn’t merely say, “The courtroom has determined in opposition to you,” and finish the matter. These causes matter as a result of they permit the individual to grasp the judgment, establish attainable errors and, the place acceptable, enchantment. Monetary AI creates an analogous drawback exterior the courtroom.
A borrower might haven’t any listening to earlier than an automatic credit score resolution. There could also be no human dialog and no alternative to clarify an uncommon circumstance, at the same time as the choice seems on a display screen.
If the system is incorrect, what does the person problem? That is one purpose transparency pertains to the rule of regulation. A choice that can’t be meaningfully questioned turns into troublesome to tell apart from an train of arbitrary energy. The thinker John Rawls famously handled the power to offer public causes as central to respectable establishments, and jurisprudence has lengthy linked reason-giving to accountability. AI doesn’t get rid of that precept merely as a result of the decision-maker is statistical, and if something, automation makes it extra vital.
The Black Field Downside in Banking
This turns into significantly troublesome with black field fashions in banking as a result of conventional credit score scoring typically depends on comparatively comprehensible variables. Black-box modelling in banking refers to utilizing an algorithm or AI system to make monetary selections when the reasoning behind its output is troublesome for people to grasp or clarify. Revenue, debt, compensation historical past, and current obligations might be defined to a buyer with out a lot problem, however trendy machine-learning techniques can function in another way, and a mannequin might study 1000’s of variables and uncover complicated relationships between them. Some fashions might also produce extremely correct predictions with out providing an intuitive account of why a selected individual obtained a selected rating, creating a real trade-off.
An easier mannequin could also be simpler to grasp however much less predictive, whereas a fancy mannequin might establish dangers {that a} human analyst would miss however be significantly tougher to clarify. The EU AI Act displays this reasoning: AI techniques used to judge the creditworthiness or credit score rating of pure individuals are typically categorized as high-risk as a result of they’ll decide entry to monetary sources and important companies.
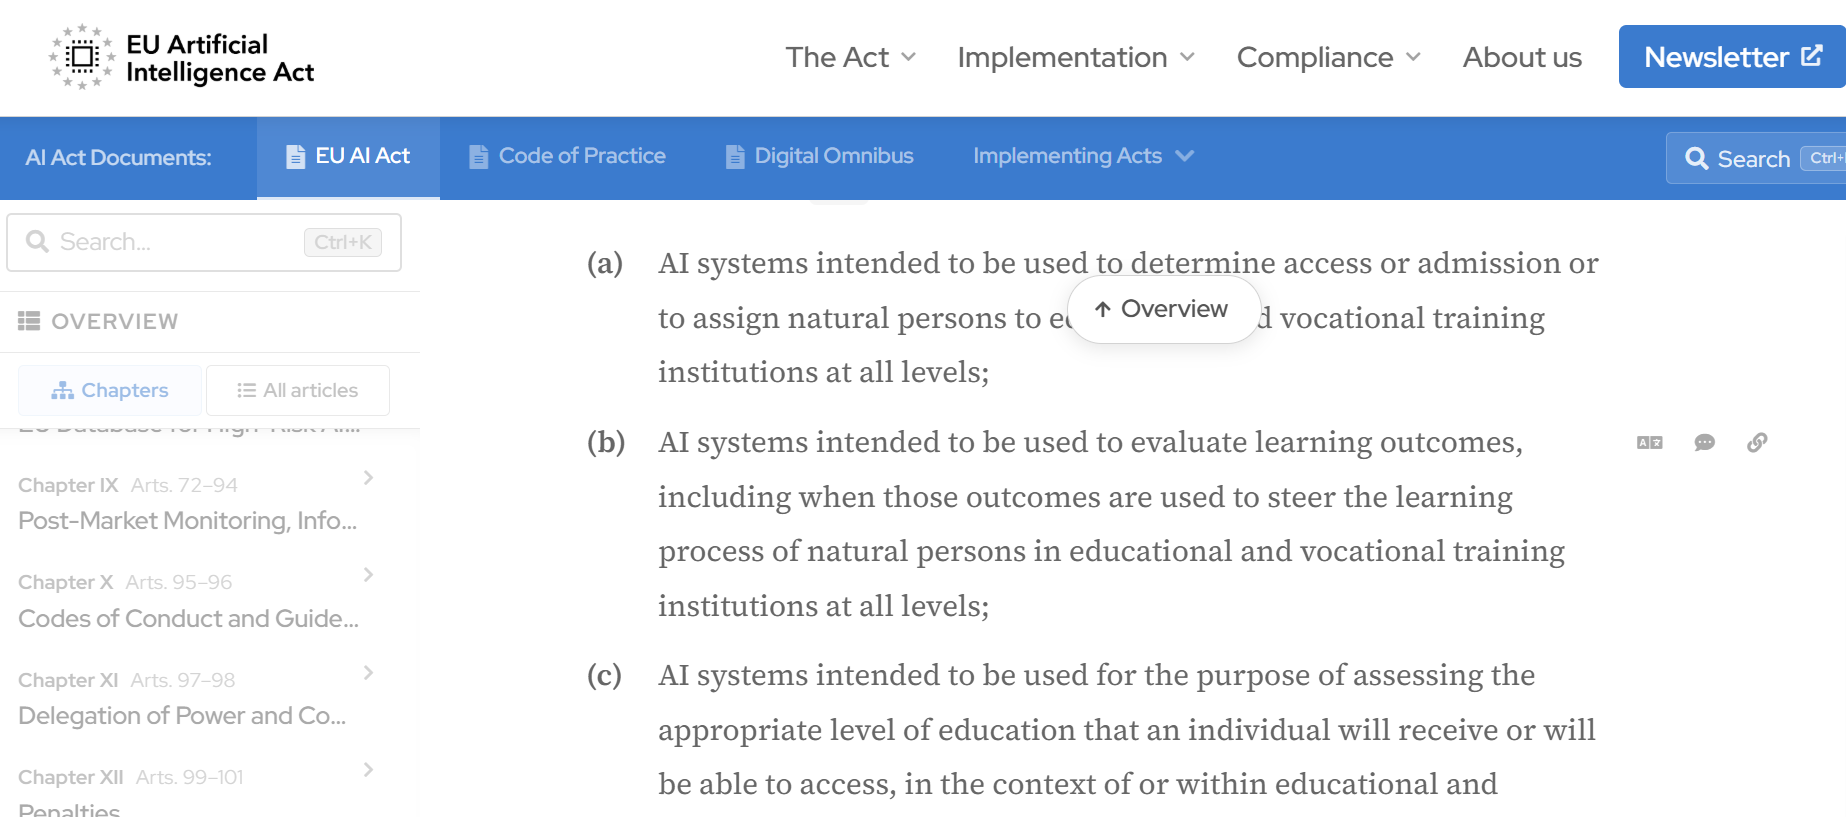
The regulation particularly acknowledges the dangers of discrimination and the chance that AI techniques might reproduce historic patterns of drawback or create new discriminatory results.
Does a Borrower Deserve a Purpose If the Mannequin Can’t Give One?
That is maybe the toughest query as a result of when a financial institution makes use of an AI mannequin that’s considerably extra correct than its older scoring system, its engineers can’t produce a totally satisfying clarification for each particular person prediction. However ought to the financial institution use it anyway? From a purely consequentialist perspective, there’s an argument for doing so, and if the mannequin reduces defaults and permits the financial institution to supply cheaper credit score to extra individuals, its general penalties might be helpful. A rights-based method raises a unique concern, and the person will not be merely an enter right into a statistical system however an individual topic to a choice.
That creates what is perhaps referred to as an ethical demand for transparency in AI finance. Individuals mustn’t essentially have a proper to know each inner calculation, however they need to have sufficient data to grasp the fabric causes affecting their remedy.
America Takes a Sensible Method
The US affords a helpful instance as a result of its method focuses much less on a basic philosophical “proper to clarification” and extra on current consumer-credit regulation. The Equal Credit score Alternative Act and Regulation B require collectors to offer particular causes when taking antagonistic motion in opposition to customers, with the Shopper Monetary Safety Bureau explicitly stating in 2023 that lenders can’t keep away from this obligation just because they use synthetic intelligence or complicated algorithms. If a black-box system makes it troublesome to establish the precise purpose for a denial, that problem doesn’t excuse the lender from offering the legally required clarification.
A financial institution can’t merely inform a borrower: “Your utility failed our inner scoring mannequin,” as a result of that describes the mechanism slightly than the rationale. The borrower wants one thing nearer to: “Your utility was declined as a result of your current debt obligations have been too excessive relative to your verified revenue.”
The second clarification provides the individual one thing they’ll perceive and probably appropriate and likewise provides the financial institution one thing to defend.
What In regards to the UK and Rising Markets?
The UK has taken a extra principles-based route, slightly than creating one sweeping AI regulation equal to the EU AI Act. UK monetary regulators have been exploring how current obligations round shopper safety, governance, accountability and mannequin danger apply to AI.
The FCA’s analysis into AI-assisted credit score selections is especially invaluable as a result of it doesn’t assume {that a} theoretically explainable system robotically produces a helpful clarification for strange individuals. Its experiments discovered that completely different explanations modified how successfully customers may establish errors.
The Deeper Philosophical Downside
Fashionable liberal societies typically settle for that energy requires causes as a result of, as governments justify legal guidelines, courts give judgments, and regulators clarify enforcement actions, administrative businesses should present causes for selections affecting residents, and such justification will not be merely instructional as a result of it seeks to restrict arbitrary energy
Monetary establishments traditionally occupied a unique place, however they too train vital financial energy, and an automatic lending system can decide entry to capital with out ever talking to the individual affected. If that energy turns into more and more automated, clarification turns into one of many mechanisms via which society retains energy answerable.
This doesn’t imply each resolution have to be explainable in excellent human phrases, nevertheless it implies that opacity mustn’t turn out to be an alternative to accountability.
The Way forward for XAI in Finance
The way forward for monetary AI will most likely not be a alternative between fully clear fashions and fully opaque ones. It is going to be a query of proportionality, and the larger the results of an automatic resolution, the stronger the justification for significant clarification, human oversight and avenues of enchantment.
The EU is transferring towards express rights and high-risk AI obligations, whereas the US is making use of current credit score regulation to more and more complicated algorithms. The UK is testing which explanations truly assist customers perceive and problem AI-assisted selections. Whereas these approaches differ, they converge on one precept: a monetary establishment can’t merely blame the machine for a consequential resolution.
That will ultimately be a very powerful thought behind explainable AI finance regulation. The aim of XAI is to not make synthetic intelligence confess each secret inside its structure however to protect one thing older than AI itself: the precept that an individual affected by the train of energy deserves a purpose.
A borrower doesn’t want to grasp each parameter in a neural community, however they do have to know what counted, why it counted, whether or not the knowledge was appropriate, and what they’ll do if the choice was incorrect. That is the place explainability turns into greater than a technical desire. It turns into a situation of lawful, accountable, and morally defensible finance.
Disclaimer: This text is meant solely for informational functions and shouldn’t be thought-about buying and selling or funding recommendation. Nothing herein needs to be construed as monetary, authorized, or tax recommendation. Buying and selling or investing in cryptocurrencies carries a substantial danger of monetary loss. At all times conduct due diligence.
Loved this? Bookmark DeFi Planet, discover associated subjects, and comply with us on Twitter, LinkedIn, Fb, Instagram, Threads, and CoinMarketCap Group for seamless entry to high-quality business insights.
Take management of your crypto portfolio with DEFI PLANET PRO, DeFi Planet’s suite of analytics instruments.


