Final week’s expertise selloff introduced a query from the bond market into sharper focus: how a lot will it price to maintain financing the AI growth?
The warning got here from bonds
CoreWeave, which offers computing capability to AI clients, noticed a few of its bond yields attain round 15% final week. Traders have been demanding roughly 10% above US Treasury yields: a considerable premium for taking the corporate’s credit score danger.
Its present fixed-rate curiosity funds haven’t modified. However its subsequent spherical of borrowing may very well be far more costly. For an organization shopping for chips and leasing information centres to develop quickly, robust demand must be matched by inexpensive financing.
That is essential for shareholders too. Increased curiosity prices depart much less money for development, whereas issuing new shares to fund enlargement can dilute present buyers.
Why this issues past CoreWeave
CoreWeave is already junk-rated, however financing issues additionally attain bigger expertise corporations held throughout retail portfolios.
Oracle is price watching as a result of its AI enlargement requires substantial funding and its shares sit within the S&P 500. A fall in Oracle subsequently weighs on the index in proportion to its weight, affecting buyers in funds monitoring it even when they don’t personal Oracle immediately. The larger danger is that comparable issues unfold to different giant expertise holdings.
Oracle stays funding grade, though Moody’s has a damaging outlook and S&P charges it only one notch above junk. A downgrade shouldn’t be inevitable, however buyers want to look at how rising buyer orders translate into money after infrastructure spending and curiosity funds.
For shareholders, the excellence is more and more between corporations that may comfortably finance enlargement and people whose development is dependent upon continued entry to recent capital.
Your chip inventory is related
For shareholders, the danger is that larger borrowing prices pressure AI corporations to chop spending, leaving their suppliers with fewer orders.
CoreWeave buys Nvidia-powered gear and rents amenities from corporations together with Utilized Digital and Core Scientific. Delayed enlargement might subsequently have an effect on chip purchases, rental earnings and development exercise.
These corporations have completely different contracts and monetary protections. They won’t essentially endure equally. However proudly owning a chipmaker, a cloud supplier and a data-centre developer can nonetheless depart a portfolio depending on the identical spending cycle.
What earnings want to indicate
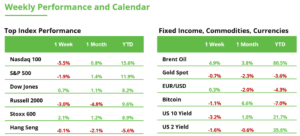
The Nasdaq 100 fell 5.5% final week. Earnings now must reassure buyers that AI spending is supporting worthwhile development.
Watch money circulation after capital expenditure, adjustments to funding budgets and administration’s financing plans. Bigger spending bulletins alone might not be sufficient to elevate shares.
We stay constructive on worthwhile expertise leaders, however selective. Sturdy stability sheets present flexibility; they don’t take away valuation danger.
The funding takeaway
Keep selective on AI. Prioritise sustainable money technology, manageable debt repayments and a reputable route from funding to returns. Verify valuations too: monetary power doesn’t make each share worth engaging.
For present holdings, ask three questions:
Can the enterprise fund its plans with out repeated fundraising?
Would slower AI development materially weaken its earnings?
How a lot of my portfolio is dependent upon the identical clients and spending budgets?
Whereas a bond-market warning is a cause to analyze, it’s not an computerized instruction to promote. Sturdy earnings and accessible funding might stabilise sentiment. The larger concern can be weaker money circulation arriving simply as refinancing turns into more durable.
Large Present, Weak Numbers? Tesla Has to Ship
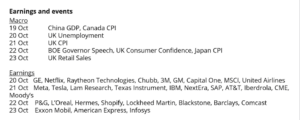
The spectacular presentation of the brand new Tesla Roadster 2 with SpaceX thrusters has made main headlines. Nonetheless, forward of Tesla’s quarterly outcomes on Wednesday after the market shut, the occasion might additionally function a distraction. Different components will matter extra.
What Traders Ought to Watch at Tesla
Automobile deliveries and income
Margins amid inflation and worth competitors
Progress in autonomous driving and robotics
Shopper sentiment as an indicator of client demand
Free money circulation after the billions invested in AI information facilities
Analysts anticipate income of round $27.8 billion. Earnings per share are anticipated to fall to round $0.44 to $0.45. The important thing query is how a lot money Tesla really generates after its heavy funding spending.
Technical Restoration at Threat
Tesla shares fell 7.3% final week to $355 and moved again under the 20-week transferring common at round $366. It’s nonetheless buying and selling round 20% above its July low. Previous to this, the inventory had shaped an ABC correction after reaching a file excessive of $496 in December 2025.
For the chart to enhance sustainably, Tesla should overcome a number of resistance ranges. First, the inventory must reclaim the 20-week transferring common, adopted by the 50-week transferring common at $396. Above that, an essential resistance zone awaits round $410.
Within the short-term, the danger of one other decline towards the July low has elevated. Consumers want additional affirmation earlier than a medium-term change in course might be mentioned.
SpaceX may even launch its outcomes on Tuesday after the US market shut.
Tesla, weekly chart. Supply: etoro
Credit score Markets Are Getting Nervous
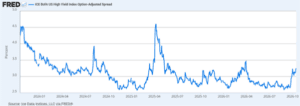
The US Excessive Yield OAS reveals the extra curiosity premium buyers demand for US company bonds with low credit score high quality in contrast with US authorities bonds. A slim unfold alerts restricted concern about danger, whereas a wider unfold factors to rising worries about defaults, financing and the economic system.
The unfold at the moment stands at round 3.2 proportion factors, up from roughly 2.6 proportion factors on the finish of August. This stage shouldn’t be but alarming from a long-term perspective. Nonetheless, the sharp enhance reveals that credit score markets have gotten extra cautious.
Rising spreads make financing costlier for corporations with excessive capital wants. This significantly impacts the enlargement of information facilities, chip manufacturing and different areas of AI infrastructure. Increased financing prices can weigh on funding, margins and anticipated earnings. The credit score market is subsequently changing into an essential stress check for the AI story. Sturdy income development shouldn’t be sufficient if that development turns into too costly or troublesome to finance.
A big widening of the unfold would sign decrease danger urge for food and better default dangers. A stage of 4% or extra can be a a lot stronger warning sign, though it might not mechanically mark a disaster threshold. Traders ought to subsequently assess the unfold along with bond yields, credit score default swaps, banks and company steerage.
An extra enhance might weigh significantly on extremely valued expertise shares. Firms with excessive debt, weak money circulation or main funding wants can be particularly weak. Stabilization within the unfold, then again, would supply short-term reassurance for fairness markets.
For long-term buyers, the important thing query is whether or not the widening unfold stays a standard repricing or develops into broader credit score stress.
Bitcoin is shedding excesses, however the restoration stays unconfirmed
Bitcoin is holding close to $81,500 in a market displaying more and more combined alerts. Massive holders have collected almost 86,000 BTC since mid-September, whereas promoting stress from long-term holders is easing. Nonetheless, ETFs have recorded round $760 million in outflows since October 7, and stablecoin provide has declined barely. Accumulation is going down, however we’re nonetheless not seeing sufficient recent capital getting into the market.
In derivatives, almost $950 million in liquidations on October 15 helped scale back extra leverage. Funding charges stay contained, and there are not any indicators of widespread capitulation. Nonetheless, danger stays concentrated under $80,000, the place roughly $1.6 billion in lengthy positions may very well be weak to liquidation.
The macro backdrop shouldn’t be serving to both. With US inflation at 3.7%, the 10-year Treasury yield round 5.1%, and the Fed sustaining a restrictive stance, monetary situations proceed to weigh on danger belongings. Ethereum and altcoins stay significantly weak.What issues subsequent? For bitcoin, the $80,000–$80,400 space is a crucial assist zone. A sustained break under might carry $78,000 into focus. On the upside, reclaiming $84,200–$85,000 alongside renewed ETF inflows would strengthen the restoration case, though $88,000 might appeal to recent promoting stress. For ethereum, the $2,500–$2,560 space stays a key resistance zone.
The subsequent ETF circulation figures and the Fed assembly on October 28 might be essential occasions to observe.
Bitcoin’s positioning seems to be more healthy following the latest discount in leverage, however a sustainable restoration shouldn’t be but confirmed. Stronger spot demand, renewed institutional inflows and bettering liquidity situations would supply extra convincing proof of a shift in momentum. Till then, draw back dangers stay, significantly for extra unstable altcoins.