Staking was presupposed to strengthen Ethereum exchange-traded funds (ETFs), however BlackRock’s early outcomes present buyers nonetheless favor its unique fund.
When US spot Ethereum ETFs launched in July 2024, the absence of staking was extensively recognized as certainly one of their largest structural disadvantages. Buyers shopping for the funds gained publicity to ETH’s value however forfeited the rewards obtainable to holders who dedicated their tokens to securing the Ethereum community.
On the time, JPMorgan cited the elimination of staking from ETF filings as one cause it anticipated weaker demand than for Bitcoin funds. BitMEX Analysis equally argued that institutional buyers may discover non-staking merchandise much less engaging, whereas Galaxy Digital estimated that giving up staking represented a significant alternative price for ETF buyers.
BlackRock now presents an early take a look at of that argument.
Its iShares Ethereum Belief ETF (ETHA) gives easy publicity to ether with out staking. The newer iShares Staked Ethereum Belief ETF (ETHB) stakes a part of its holdings and distributes a portion of the ensuing revenue to shareholders.
Up to now, including yield has not overturned the hierarchy.
ETHA held about $8.96 billion in web belongings on Sept. 11, in contrast with roughly $1.05 billion for ETHB, BlackRock fund knowledge present.
The distinction is even bigger in secondary-market buying and selling: ETHA generated an estimated $1.86 billion of share turnover that day based mostly on quantity multiplied by its closing value, roughly 30 occasions ETHB’s $61.8 million.
ETHB can be paying buyers. The fund listed a distribution of $0.036487 per share payable Sept. 10 after starting to earn staking rewards in Could.
But ETHA attracted $148.8 million of web inflows on Sept. 11, in contrast with $18.3 million for ETHB, Farside Buyers knowledge present.
The comparability comes with an vital limitation. ETHA has had considerably extra time to build up belongings, buying and selling relationships, and institutional adoption, whereas ETHB remains to be constructing its monitor file. Its roughly $1 billion asset base additionally represents significant demand for a more recent product.
Nonetheless, ETHA’s continued inflows after staking revenue grew to become obtainable problem the stronger model of the thesis that lacking yield was the principle constraint on Ethereum ETF demand.
Staking removes one handicap, however not ETHA’s head begin
ETHB removes a lot of the opportunity-cost drawback that formed criticism of the unique Ethereum ETF construction. It can’t instantly replicate the liquidity ETHA has amassed since turning into one of many first US spot Ethereum ETFs.
BlackRock reported a 30-day median bid-ask unfold of 0.05% for ETHA as of Sept. 11, in contrast with 0.06% for ETHB. That distinction is small, however the a lot wider disparity in buying and selling exercise offers establishments considerably extra capability to enter and exit bigger ETHA positions.
Every day flows have but to point out a sustained migration towards the staking product.
Each funds recorded no web flows on Sept. 8 and attracted capital on Sept. 9. ETHA suffered an outflow on Sept. 10 whereas ETHB gained belongings, however each returned to inflows the following day, with ETHA attracting considerably extra money.
These actions can’t set up whether or not particular person buyers are rotating between the merchandise. ETF move knowledge establish creations and redemptions on the fund stage however don’t reveal whether or not an investor promoting ETHA subsequently used the proceeds to buy ETHB.
That distinction issues if staking ultimately modifications the aggressive stability. A sustained interval of ETHB creations accompanied by ETHA redemptions would supply a lot stronger proof that buyers are actively exchanging less complicated publicity for yield-bearing publicity.
Yield introduces prices and one other layer of liquidity administration
Staking additionally offers ETHB a extra difficult financial construction than merely including yield to ETHA.
About 75.85% of ETHB’s ether was categorized as staked as of Sept. 10, whereas roughly 24.15% remained unstaked. The unstaked portion gives liquidity for fund operations and redemptions with out requiring BlackRock to attend for ether to exit Ethereum’s staking course of.
Buyers additionally face two separate layers of costs.
ETHB carries a typical annual sponsor payment of 0.25%, the identical headline charge as ETHA, though a short lived waiver reduces the payment to 0.12% on its first $2.5 billion of belongings for 12 months starting March 12.
Staking rewards carry one other cost. An April prospectus complement units the mixture staking payment at 10% of gross staking consideration, down from an earlier 18%.
The charges apply to totally different bases. The sponsor payment is assessed in opposition to fund belongings, whereas the staking payment is deducted from rewards generated by taking part in Ethereum’s proof-of-stake community.
Distributions are additionally conditional, not a hard and fast yield. BlackRock can think about staking consideration obtained, authorized necessities, and the fund’s operational and liquidity wants when figuring out funds.
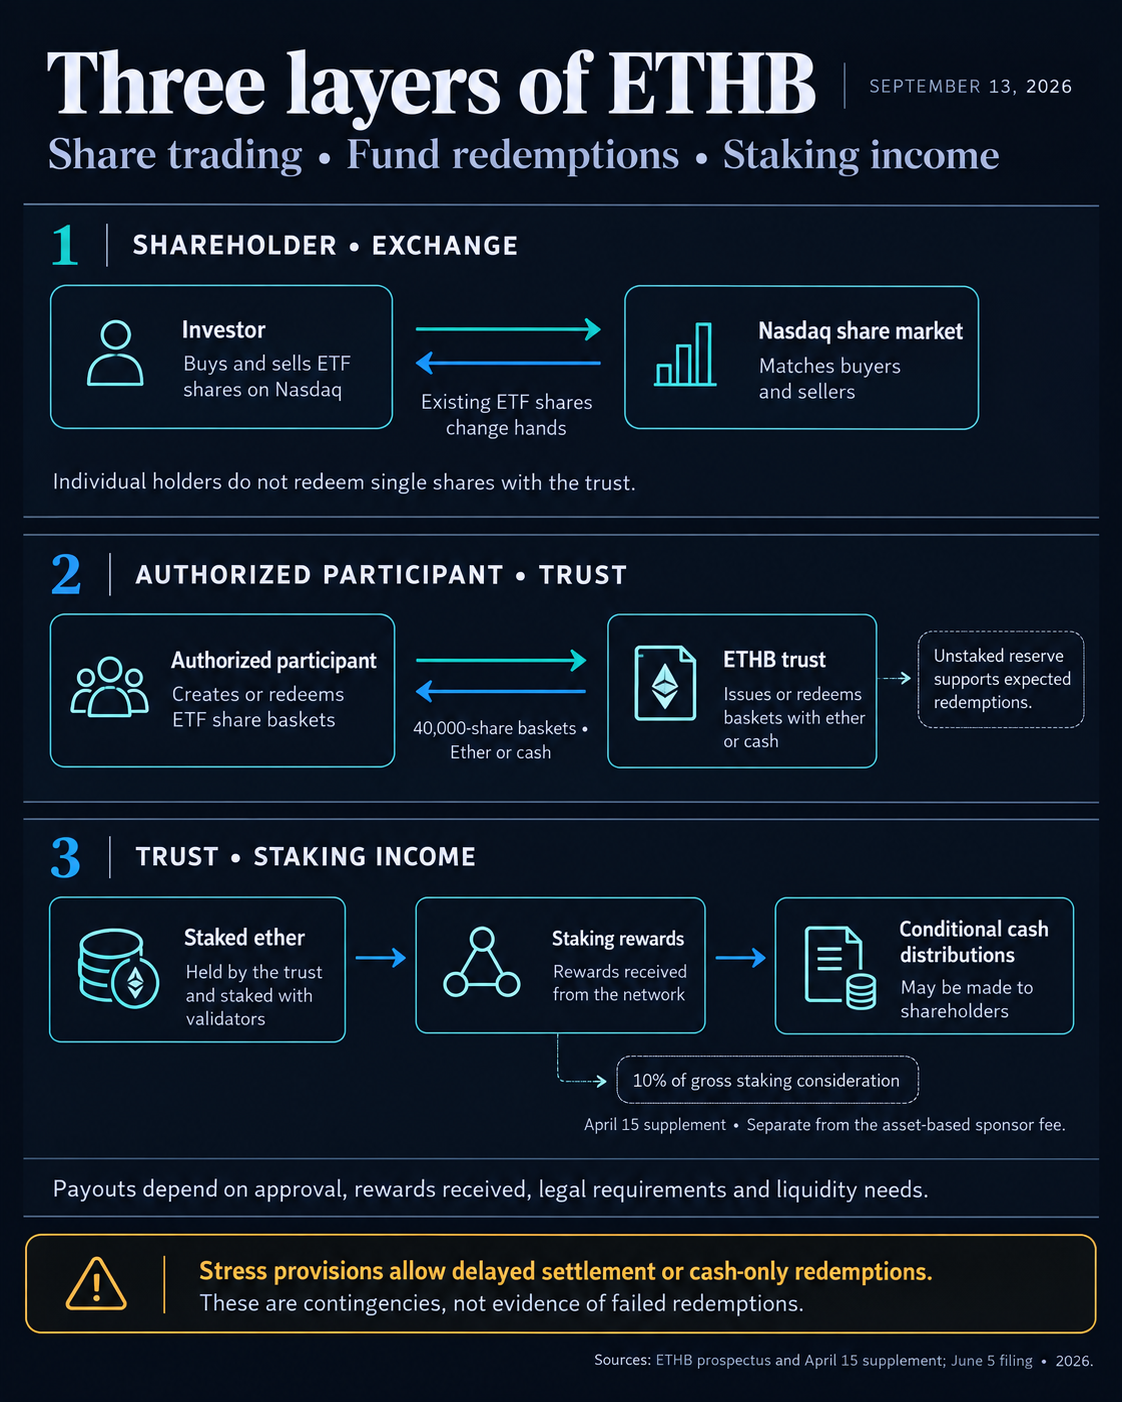
The construction introduces further redemption issues. Beneath confused situations, ETHB’s prospectus permits delayed settlement or cash-only redemptions when staking exit occasions or obtainable liquidity make atypical settlement tougher.
These trade-offs put the staking thesis to a harder take a look at than whether or not buyers like receiving further revenue.
ETHB should generate sufficient after-fee worth to steer buyers to decide on a youthful, less-traded automobile over an incumbent with almost $9 billion in belongings.
The following sign shall be whether or not ETHB can convert its distribution characteristic into sustained creations slightly than episodic demand round payouts. If that occurs whereas ETHA begins shedding belongings, the staking thesis could have stronger help.
Till then, BlackRock can seize each preferences: buyers prioritizing ETHA’s established liquidity and people prepared to just accept further complexity to earn staking revenue by ETHB.


