Two days after the US Senate did not advance the CLARITY Act, federal regulators opened two narrower routes for crypto-linked market entry underneath current legislation.
The Securities and Change Fee created a five-year path for permissioned venues to commerce tokenized US shares via automated market makers. The Commodity Futures Buying and selling Fee broadened employees no-action aid so qualifying software program suppliers can join customers to regulated derivatives markets with out registering as introducing brokers for the lined exercise.
The actions can assist actual merchandise, however they don’t recreate market-structure laws. The SEC route is capped and conditional. The CFTC route nonetheless depends on registered derivatives companies for onboarding, buying and selling and custody, and it rests on a employees place that may change.
The SEC turns current authority right into a five-year take a look at
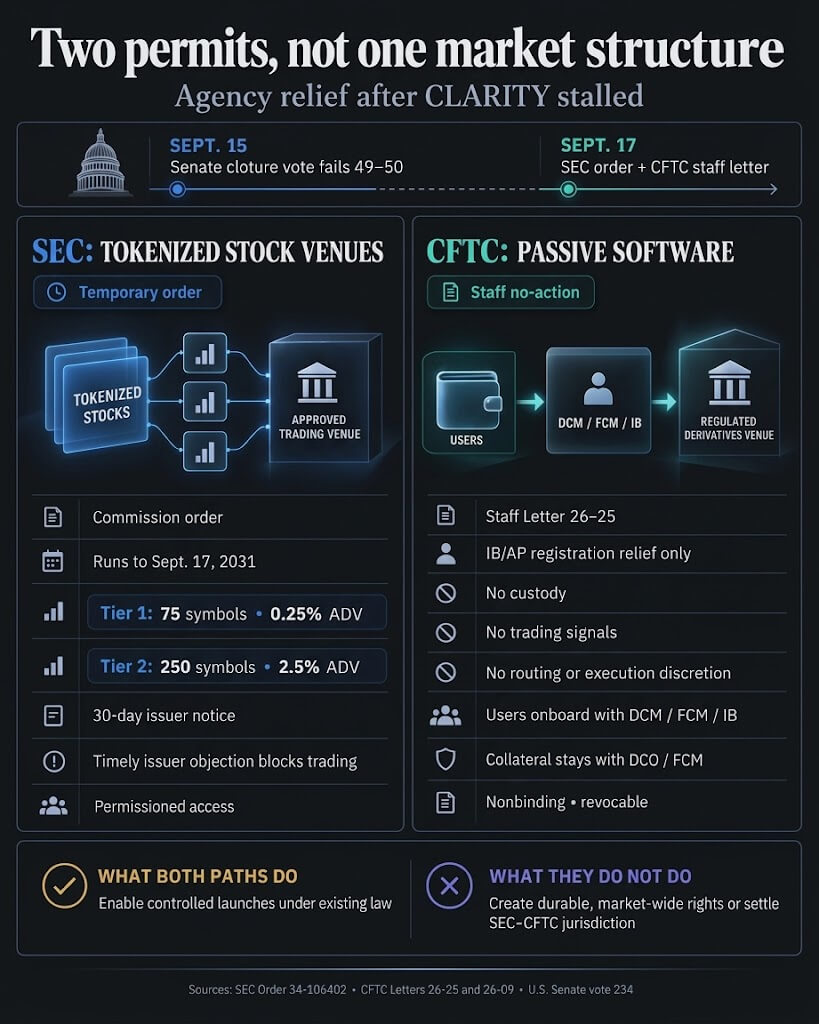
The timing was direct. On Sept. 15, senators voted 49-50 in opposition to cloture on the movement to proceed to H.R. 3633, based on the official roll name. That was a procedural failure to advance the CLARITY Act, not a remaining vote on the invoice’s deserves.
On Sept. 17, SEC Chairman Paul Atkins related the congressional setback to the Fee’s subsequent transfer. In a press release accompanying the Innovation Exemption, Atkins stated the company was performing inside its current statutory authority. He additionally characterised the exemption as a bridge that needs to be adopted by sturdy rulemaking.
The SEC order creates a brand new class referred to as a Tokenized Securities Venue, or TSV. A qualifying venue can convey patrons and sellers collectively via permissioned automated market maker liquidity swimming pools with out being handled as an change underneath the Change Act. Sure companies that offer tokenized inventory from proprietary accounts also can obtain conditional aid from the seller definition for that exercise.
The exemptions run via Sept. 17, 2031, until the SEC modifies them. Their limits make the experiment intentionally small relative to the US fairness market.
Throughout a TSV and its associates, Tier 1 shares are restricted to 75 symbols and not more than 0.25% of the prior month’s common day by day share quantity in every related inventory. Tier 2 shares are restricted to 250 symbols and a couple of.5% of common day by day share quantity.
Eligible tokenized shares should protect the financial and governance rights hooked up to equal conventional shares, together with dividend and voting rights. Artificial-exposure tokens, rights, warrants, major issuances and preliminary choices don’t qualify.
Issuers additionally obtain a direct management level. Earlier than a TSV can commerce inventory tokenized by an unaffiliated third social gathering, the venue should notify the issuer and wait at the least 30 calendar days after receipt. An objection delivered inside that window blocks the tokenized inventory from buying and selling on that TSV.
The blockchain could also be public and permissionless, however the market is permissioned. TSVs should set entry requirements, confirm contributors or pockets addresses, and disclose when entry will be denied or restricted. Good contracts have to be public and auditable, whereas the venue stays chargeable for delegated verification.
The order replaces full change oversight with tailor-made situations fairly than eradicating market safeguards. TSVs should publish transaction knowledge, maintain information, cease buying and selling when the underlying inventory is halted on its major change, disclose operational dangers and report vital programs occasions.
Different legal guidelines nonetheless apply. The order preserves Securities Act necessities, federal antifraud and antimanipulation guidelines and sanctions compliance. SEC, self-regulatory group and anti-money laundering duties can nonetheless apply to contributors primarily based on their actions. The exemption covers the outlined TSV mannequin, not securities exercise exterior it.
The CFTC opens an interface whereas registered companies maintain management
The Commodity Futures Buying and selling Fee‘s Market Contributors Division moved on the identical day with Letter 26-25. The letter generalizes aid that the division granted to Phantom in Letter 26-09 in March. The sooner place utilized solely to Phantom; the brand new one is out there to passive software program suppliers on considerably the identical phrases and isn’t restricted to crypto wallets.
A qualifying supplier can show market and place knowledge, market specific derivatives contracts and registered companies, solicit customers, obtain income sharing or transaction-based charges, and transmit user-directed orders. These actions might in any other case set off introducing-broker or associated-person registration.
The aid is slim. The software program supplier can not maintain buyer property, generate specific purchase or promote alerts, or train discretion over order routing or execution. Letter 26-25 addresses solely whether or not the division will suggest enforcement for failure to register as an introducing dealer or related individual for the lined actions. It doesn’t present a common exemption from different registration classes or legal guidelines.
Customers have to be onboarded straight with a delegated contract market, futures fee service provider or introducing dealer. They have to be capable of attain that registered agency independently of the software program supplier. Funds securing derivatives positions stay with a derivatives clearing group and/or a clearing-member futures fee service provider.
The supplier additionally assumes situations overlaying battle and threat disclosures, advertising controls modeled on Nationwide Futures Affiliation guidelines, recordkeeping, regulatory notices and joint legal responsibility with every collaborating registrant for violations related to the lined exercise.
This creates a clearer position for wallets and different interfaces with out transferring the regulated market’s core capabilities into the software program layer. A supplier could make derivatives simpler to find and entry, however the designated market handles buying and selling, registered companies onboard customers, and a DCO or FCM holds collateral.
The authorized basis can be much less sturdy than the SEC’s time-limited Fee order. Letter 26-25 represents the views of 1 CFTC division, just isn’t binding on the Fee and could also be modified, suspended or terminated. Until modified earlier, it runs solely till related Fee rulemaking or steering takes impact.
Helpful permits nonetheless fall in need of market construction
The SEC and CFTC actions remedy totally different registration issues. Their shared function is that each create conditional working area with out establishing common market-wide rights.
For tokenized shares, entry will depend on a TSV’s permissioning requirements, image and quantity caps, issuer objections and persevering with compliance with the order. For regulated derivatives, the interface supplier should stay passive whereas customers, collateral and execution keep inside registered market infrastructure.
That distinction makes the brand new routes helpful for managed launches. A agency can construct to specified situations as an alternative of ready for Congress. Customers could achieve simpler paths to tokenized shares or regulated derivatives. Regulators can observe exercise earlier than writing everlasting guidelines.
The identical design creates uncertainty. Neither motion settles the broader allocation of authority between the SEC and CFTC. Neither grants an unconditional proper for a venue, pockets or consumer to enter these markets. Different relevant federal and state obligations stay exterior the slim aid, and future company interpretations might change the economics of counting on it.
No firm is called within the SEC order or CFTC Letter 26-25 as dedicated to launch underneath the Sept. 17 pathways. The CFTC letter says solely that unnamed equally located suppliers and their counsel made inquiries after the Phantom aid.
The primary sensible take a look at might be public commitments. For the SEC route, meaning notices from operators keen to just accept the caps, disclosure duties and issuer-objection course of, adopted by proof that liquidity can develop inside these limits. For the CFTC route, it means software program suppliers signing agreements with registered derivatives companies, submitting the required undertakings and providing an interface that is still passive in observe.
Market conduct will then reveal whether or not conditional entry can scale. Issuer objections, participant onboarding, liquidity, transaction volumes and any regulatory modifications will present whether or not the pathways turn out to be sturdy market channels or stay experiments.
The companies have demonstrated that US crypto entry can develop with out a new act of Congress. They haven’t proven that short-term exemptions and revocable employees aid can present the understanding, uniformity or jurisdictional settlement that laws might ship.


